Types of life insurance explained
There are really two families of cover. Term insurance protects you for a set number of years and is the cheaper option. Whole of life cover lasts for life and is designed to pay out when you die, provided the policy remains in force and its terms are met, so it costs more. This guide walks through each type, with clear tables of what they cover and what they cost.
Get my quoteThe short answer
Almost every life insurance policy is a version of one of two ideas. Term cover protects you for a fixed number of years and pays out only if you die within that time. It is cheaper, because there is a real chance it never pays. Whole of life cover has no end date and is designed to pay out when you die, provided the policy remains in force and its terms are met, so the price is higher.
Everything else, decreasing term, family income benefit, over 50s plans, joint policies, is a variation on those two. Below, each type is explained with what it covers and what it costs.
Life insurance can seem to come in dozens of varieties, but almost all of them are a version of two ideas: cover that lasts a set time, and cover that lasts for life. Get that distinction and the rest falls into place.
Term life insurance
Term life insurance covers you for a fixed number of years, the term, and pays a tax free lump sum only if you die within it. If you outlive the term, it pays nothing and simply ends. It is by far the most popular type, with around 1.4 million new policies taken out in 2025, because it is cheap and it matches most real needs, like covering a mortgage or raising children.4 It comes in a few forms.
- Level term. The payout stays the same for the whole term. Good for family protection or an interest only mortgage, where the amount needed does not fall.
- Decreasing term. The payout falls over time, roughly tracking a repayment mortgage down. It is the cheapest cover, and is often sold as mortgage life insurance.
- Increasing term. The payout rises each year, usually in line with inflation, to protect the real value of the cover. It costs more than level term.
- Family income benefit. Instead of one lump sum, it pays your family a regular monthly income for the rest of the term. It is often cheaper than equivalent level term, and can be easier for a family to manage than a single large sum.
Whole of life insurance
Whole of life insurance has no end date. It is designed to pay out when you die, provided the policy remains in force and its terms are met, such as keeping up the premiums. Because it has no end date, it is the most expensive type, averaging about 102 pounds a month.1 It is generally used for things that do not go away, such as covering funeral costs, leaving a legacy, or paying an expected inheritance tax bill. Because of that last use, whole of life cover is often written in trust, which can keep the payout outside your estate.
Over 50s life insurance
Over 50s plans are a form of whole of life cover aimed at people aged roughly 50 to 80. The draw is guaranteed acceptance with no medical and no health questions. The trade offs are real, though. The sum is usually small, there is a waiting period in the first year or two during which only accidental death is covered, and because you pay for life, you can pay in more than the policy pays out if you live a long time. They average about 29 pounds a month.1 Treat them as a way to cover a funeral or leave a small gift, not as an investment.
Critical illness and income protection
Two other types are often bought alongside life cover, though they protect against living events rather than death.
- Critical illness cover pays a lump sum if you are diagnosed with a serious illness named in the policy, such as cancer, a heart attack or a stroke. It can be added to a life policy or bought on its own.
- Income protection pays a regular income if illness or injury stops you working, usually until you recover, retire or the policy ends. It protects your earnings rather than leaving a lump sum.
Single or joint policies
Any of these can usually be set up for one person or two. A joint life policy covers a couple and is typically around 10 percent cheaper than two single policies, but it pays out only once, usually on the first death, and then ends. Two single policies cost a little more but each pays out, which can leave the survivor still covered.
Types at a glance
The main types side by side. Costs are explained in full in the next section.
| Type | Covers you for | Payout | Cost a month | Best for |
|---|---|---|---|---|
| Level term | A set term, often 20 to 30 years | Stays the same | £25.051 | Family protection or an interest only mortgage |
| Decreasing term | A set term | Falls over time | £16.581 | A repayment mortgage |
| Family income benefit | A set term | A monthly income, not a lump sum | Often below level term | Replacing lost income for a family |
| Whole of life | Your whole life | Whenever you die, if kept in force | £1021 | Funeral costs, inheritance tax, a legacy |
| Over 50s plan | Your whole life, from age 50 | A smaller fixed sum, whenever you die after any waiting period | £29.451 | A funeral or small gift, no medical |
What each type costs
Price depends mostly on two things: the type you choose, and your age when you start. The type sets the ballpark, from decreasing term at the cheap end to whole of life at the dear end.
| Type | Average monthly cost |
|---|---|
| Decreasing term | £16.58 |
| Level term | £25.05 |
| Over 50s plan | £29.45 |
| Joint cover (level term) | £36.84 |
| Whole of life | £102 |
published 2026 UK market pricing, average monthly premiums for £150,000 of cover, all ages and smoking statuses blended.1
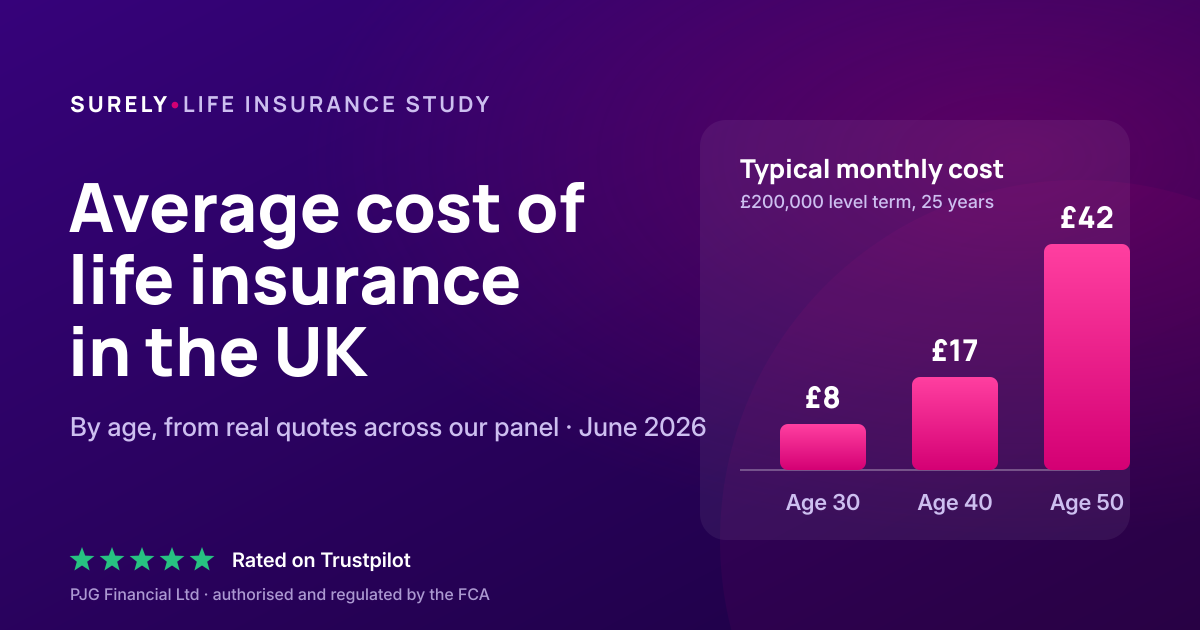
Age is the next big lever. Premiums roughly double every decade you wait, because the chance of a claim rises. This table shows how decreasing term cover climbs with age for the same cover.
| Age when you start | Typical monthly cost |
|---|---|
| Age 25 | £4 to £6 |
| Age 30 | £5 to £6 |
| Age 35 | £6 to £8 |
| Age 40 | £8 to £10 |
| Age 45 | £11 to £14 |
| Age 50 | £18 to £21 |
published 2026 UK age-based pricing, decreasing term, £150,000 of cover over 20 years, non smoker in good health.2
Smoking is the other big factor. For level term cover, a non smoker pays about 15 pounds a month on average against about 35 pounds for a smoker, more than double for the same cover.1 You can see how much life insurance costs in more detail for your own situation.
Estimate your monthly cost
An illustrative estimate for term cover. Move the sliders and tap the options to see a rough monthly price.
This is an illustrative estimate, not a quote. It is based on average UK non smoker pricing by age, scaled for your cover, type and smoker status. Your actual price depends on your health, lifestyle and the insurer. For whole of life or over 50s costs, see the table above.
Get my real quote
“Do not get lost in the names. Ask two questions. How long do I need cover for, and does it need to last for life? If the need ends when the kids are grown or the mortgage is paid, term cover is built for that and costs less. If the need lasts for life, that is what whole of life is designed for, provided the policy stays in force, and it costs more. Everything else is detail on top of those two.”
Which type is right for you
Start from the need, not the name.
- Covering a repayment mortgage: decreasing term, the cheapest fit for a falling debt.
- Protecting a family or an interest only mortgage: level term, or family income benefit if a monthly income suits better.
- Covering a funeral or an inheritance tax bill: whole of life cover, or an over 50s plan for a smaller sum with no medical.
- Worried about illness rather than death: critical illness cover or income protection.
Many people use more than one, such as decreasing term for the mortgage plus level term for the family. There is no single right answer, only the right fit for what you are protecting.
Common questions
What are the main types of life insurance?
The two main types are term cover, which lasts a set period, and whole of life cover, which lasts for life. Most other options, such as decreasing term, family income benefit and over 50s plans, are variations on those two.
Which type is cheapest?
Decreasing term is usually the cheapest, averaging about 17 pounds a month, because the payout falls over time. Whole of life is the most expensive, averaging about 102 pounds, because it has no end date.
Which type pays out whenever you die?
Whole of life cover, including over 50s plans, is designed to pay out when you die, provided the policy remains in force and its terms are met, such as keeping up the premiums. Term cover pays only if you die within the term, and nothing if you outlive it.
What is the difference between level and decreasing term?
Level term keeps the same payout for the whole term. Decreasing term reduces over time, which suits a repayment mortgage and makes it cheaper.
Do over 50s plans need a medical?
No. They are guaranteed acceptance with no medical or health questions. The trade offs are a waiting period in the first year or two and the risk of paying in more than the policy pays out if you live a long time.
Can I combine different types?
Yes. There is no limit on the number of policies you can hold, and many people combine types, for example decreasing term for the mortgage and level term for the family.
Deciding what is right for you
Two questions settle most of it. How long do you need cover for, and does the need last for life? Term cover is built for a set need, like a mortgage or young children, and costs less. Whole of life is built for a need that never goes away, like a funeral or an inheritance tax bill. From there, the exact type is matched to the shape of the need, and comparing a few insurers shows the price.
Ready to look at cover?
Get my quoteWhich type of cover is right for you depends on your personal circumstances. Cover, price and eligibility depend on your age, health, occupation and smoker status, and on insurer terms. Tax treatment depends on your circumstances and can change. Life Adviser is operated by PJG Financial Ltd, which is authorised and regulated by the Financial Conduct Authority, FRN 919697.
How we researched this guide
We write our guides from named, public UK sources and cross check the figures rather than rely on a single site. Where we say “Life Adviser analysis”, it means we have compiled and compared published data, not produced the raw figures ourselves.
The data on this page draws on:
- published 2026 UK market pricing, for average monthly premiums by type.
- published 2026 UK age-based pricing, for typical decreasing term costs by age.
- Association of British Insurers and GRiD, protection claims data 2024, for claims paid.
- Swiss Re Term and Health Watch, for the number of policies sold by type.
Cost figures are illustrative averages, not quotes. Your own price will depend on your age, health, the cover you choose and the insurer.
Life Adviser does not itself compare or recommend insurance policies. We may introduce you to one FCA-authorised adviser firm, or one of its appointed representatives. That firm can compare life insurance products and quotes from the insurers available to it and provide any advice or arrange any cover. The range of insurers considered depends on the adviser firm’s panel and may not include the whole market. The firm pays us a fee for the introduction, at no extra cost to you.
Written and reviewed by Paul Gillooly, Founder of Life Adviser. Last reviewed June 2026.
Sources
- published 2026 UK market pricing. Average monthly premiums for £150,000 of cover: decreasing term £16.58, level term £25.05, over 50s £29.45, joint level term £36.84, whole of life £102; level term non smoker £15.06 against smoker £35.02.
- published 2026 UK age-based pricing. Typical decreasing term premiums, £150,000 over 20 years, non smoker in good health, by age.
- Association of British Insurers and GRiD, protection claims data 2024, published July 2025. 97.9% of individual claims paid over the past decade; £5.32 billion paid; average individual claim £18,700. abi.org.uk
- Swiss Re, Term and Health Watch. Around 1.4 million new term assurance policies were taken out in 2025, far more than any other type. swissre.com