Does your life insurance cover death caused by war?
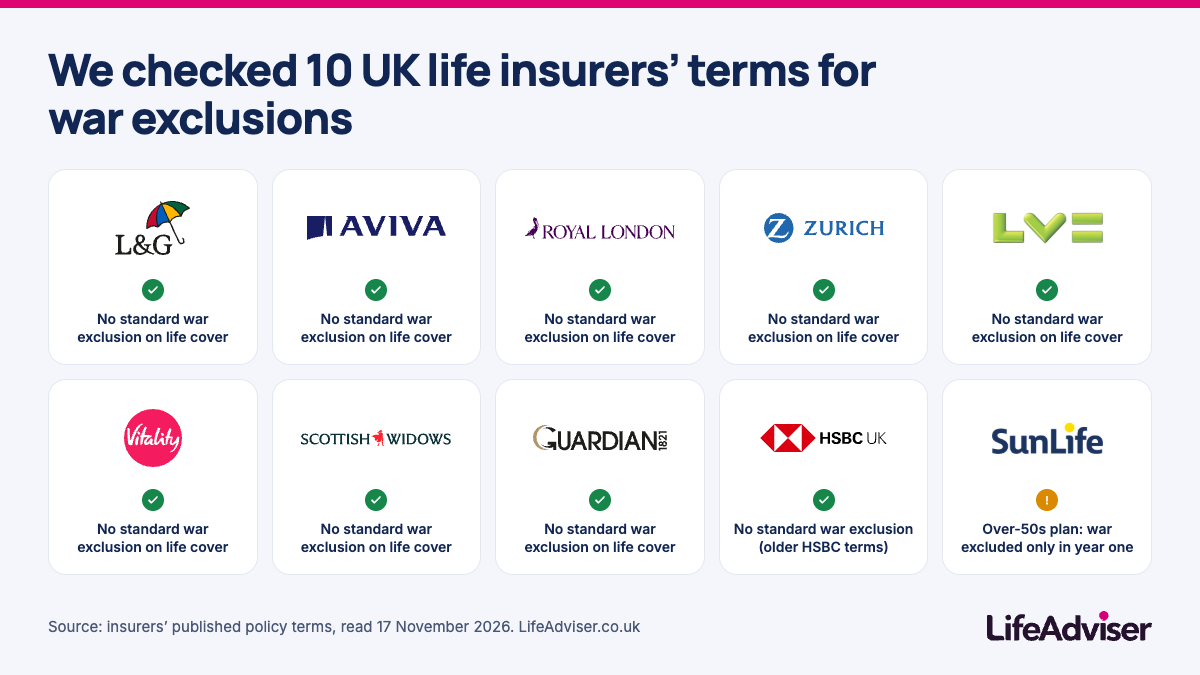
If war reached the UK, would the life insurance your family relies on still pay? We read 10 UK insurers’ published terms. None had a standard life cover exclusion for war, but some policies, extra benefits and personal exclusions need a closer look.
The quick answer
The standard life cover terms we checked had no exclusion for death caused by war. We also found no standard life cover exclusion for invasion, terrorism, or nuclear, chemical or biological events across the 10 insurers.
Check your own documents before relying on that finding. Older policies and personal exclusions can differ. Some over-50s plans, optional benefits and temporary application cover have separate war restrictions.
The 10 insurers we checked
If the UK were attacked, would civilian deaths be covered?
Yes, on the standard terms we read, it would pay; war isn’t a reason any of them gives for refusing a life claim.
The only things that could stop it are a personal exclusion on your own cover summary, or the normal rules, for example suicide in the first 12 months or wrong answers on the application.
What the 10 insurers’ terms say
We read the published individual policy terms available on 17 November 2026. HSBC Life is now Chesnara Life, and only older HSBC documents were available online. SunLife’s entry covers its over-50s plan, insured by Phoenix Life.
| Insurer | Life cover war exclusion? | Where war is mentioned |
|---|---|---|
 Legal & General | No standard exclusion | First-year over-50s cover and free temporary application cover |
 Aviva | No standard exclusion | Only as a personal critical illness exclusion for serving forces in a war zone |
 Royal London | No standard exclusion | Older over-50s wording, dropped around 2015 |
 Zurich | No standard exclusion | Not mentioned in its terms |
 LV= | No standard exclusion | Extra 50% critical illness accident payment |
 Vitality | No standard exclusion | Optional Accident and Fracture Cover |
 Scottish Widows | No standard exclusion | Not mentioned in its terms |
 Guardian | No standard exclusion | Not mentioned in its terms |
 HSBC Life, now Chesnara Life | No standard exclusion (older terms) | Not mentioned in the terms we found |
 SunLife, insured by Phoenix Life | No general exclusion in its over-50s plan | First-year accidental death payout |
LV= says, “Death is covered anywhere in the world”. Legal & General’s FAQ says its policies “do not usually exclude war risks”.
“Not mentioned” means the word war doesn’t appear anywhere in those terms, so there’s no war exclusion to rule a claim out.
What if I am called up or mobilised as a reservist?
You don’t need to tell your insurer, and your existing cover carries on as written, because none of the policies we read asks you to report a job change after cover starts and none has a standard war or military exclusion.
The one thing to check is any personal exclusion on your cover summary.
For income protection, claims are judged on the job you do just before you claim. Aviva and Zurich don’t sell income protection to the armed forces, so that matters if you’re buying new cover after joining up.
I am already serving in the armed forces. Am I covered?
You need to check the cover you were offered, because insurers assess armed forces membership and deployment when you apply.
Aviva says most non-deployed service personnel can get life cover at standard rates. Bomb disposal, air crew and special forces are treated differently. Aviva can also add a personal critical illness exclusion for serving members in an active war zone.
Aviva and Zurich do not offer income protection to armed forces members. Any personal exclusion should appear on your policy schedule or cover summary.
What if I travel, move abroad or enter a conflict area?
For life cover, the terms we read don’t stop paying because you’re abroad (LV=: “Death is covered anywhere in the world”), but you usually must tell your insurer if you move abroad.
Insurers ask about travel when you apply. Ask your insurer about the country concerned and check any personal exclusion.
Income protection may limit payments while you live outside listed countries. Do not assume the rules for life cover also apply to that benefit.
Is critical illness cover or income protection the same?
We found no standard war exclusion in either product at the eight insurers whose terms we checked for these benefits: Legal & General, Aviva, Royal London, Zurich, LV=, Vitality, Scottish Widows and Guardian.
They pay for different things. Critical illness cover pays for specified illnesses. Income protection pays an income when illness or injury prevents you working, subject to its terms.
Extra benefits need a separate check. Vitality’s optional Accident and Fracture Cover excludes war-related events and military participation. LV=’s extra 50% critical illness accident payment excludes people actively taking part in war or riot; the main critical illness claim is unaffected.
What is the first-year catch with over-50s plans?
SunLife and Legal & General restrict the full payout for war-related deaths during the first year of their over-50s plans.
In that year, full cover is for accidental death; other deaths result in premiums being returned. SunLife excludes its accidental death payout where death results from “your involvement in war or hostilities”.
Legal & General returns premiums for a first-year death caused by “War (whether declared or not), riot or civil commotion”.
After year one, both pay the full amount whatever the cause. Aviva’s over-50s terms have no war wording. Royal London dropped its older war wording around 2015, making the documents issued with an existing plan especially important.
Could war change my terms or premiums?
Not just because there’s a war.
The change clauses we read are limited to set reasons, mostly changes in the law, regulation or tax, or fixing mistakes, usually with 60 to 90 days’ notice (older HSBC terms: 30 days).
Some are wider. For example, HSBC’s older terms allow changes “for any other valid reason”; Guardian’s say they may “need to change your current terms”.
Legal & General allows changes only for legal, regulatory or tax reasons. SunLife says, “Your monthly premiums will never increase.”
Read your own policy’s change clause.
Check your own policy in three steps
- Find your documents. Get the terms issued for your policy and your personal schedule or cover summary.
- Check each benefit. Search for war, terrorism, armed forces and exclusions. Read the rules for optional extras and temporary cover. Legal & General’s free temporary application cover excludes war.
- Get an answer about your circumstances. Ask your insurer or adviser to explain unclear wording, referring to the policy and benefit concerned.
Frequently asked questions
Would life insurance pay after a terrorist attack?
Our review found no standard terrorism exclusion for life cover across the 10 insurers. Check whether your documents contain an individual restriction or different older wording.
What about a nuclear, chemical or biological attack?
No standard exclusion in any of the 10 sets of terms we read; check your own cover summary for anything personal.
What happens if my insurer goes bust?
The Financial Services Compensation Scheme says long-term insurance, which includes life insurance, is 100% protected if a UK insurer fails. See its insurance protection page in the sources below.
Does this review cover my older policy?
Only your original policy documents can confirm that. Published terms available now may differ from those issued when you bought cover.
Can an adviser help me check?
Yes. Give them both the policy terms and your personal cover summary so they can check the cover actually issued to you.
Sources
Policy terms read 17 November 2026:
- Legal & General: life, over-50s, critical illness and income protection; temporary application cover.
- Aviva: life, over-50s, critical illness and income protection; armed forces underwriting guidance.
- Royal London: life, over-50s, critical illness and income protection; older over-50s wording.
- Zurich: life, critical illness and income protection.
- LV=: life, critical illness and income protection.
- Vitality: life, critical illness, income protection and Accident and Fracture Cover.
- Scottish Widows: life, critical illness and income protection.
- Guardian: life, critical illness and income protection.
- HSBC Life: older life insurance terms.
- SunLife: over-50s policy terms.
- Legal & General: dangerous jobs FAQ, dated 20 June 2023.
- FSCS: insurance protection, read 17 November 2026.
Written by Paul Gillooly, Founder of Life Adviser. Last updated 17 November 2026.